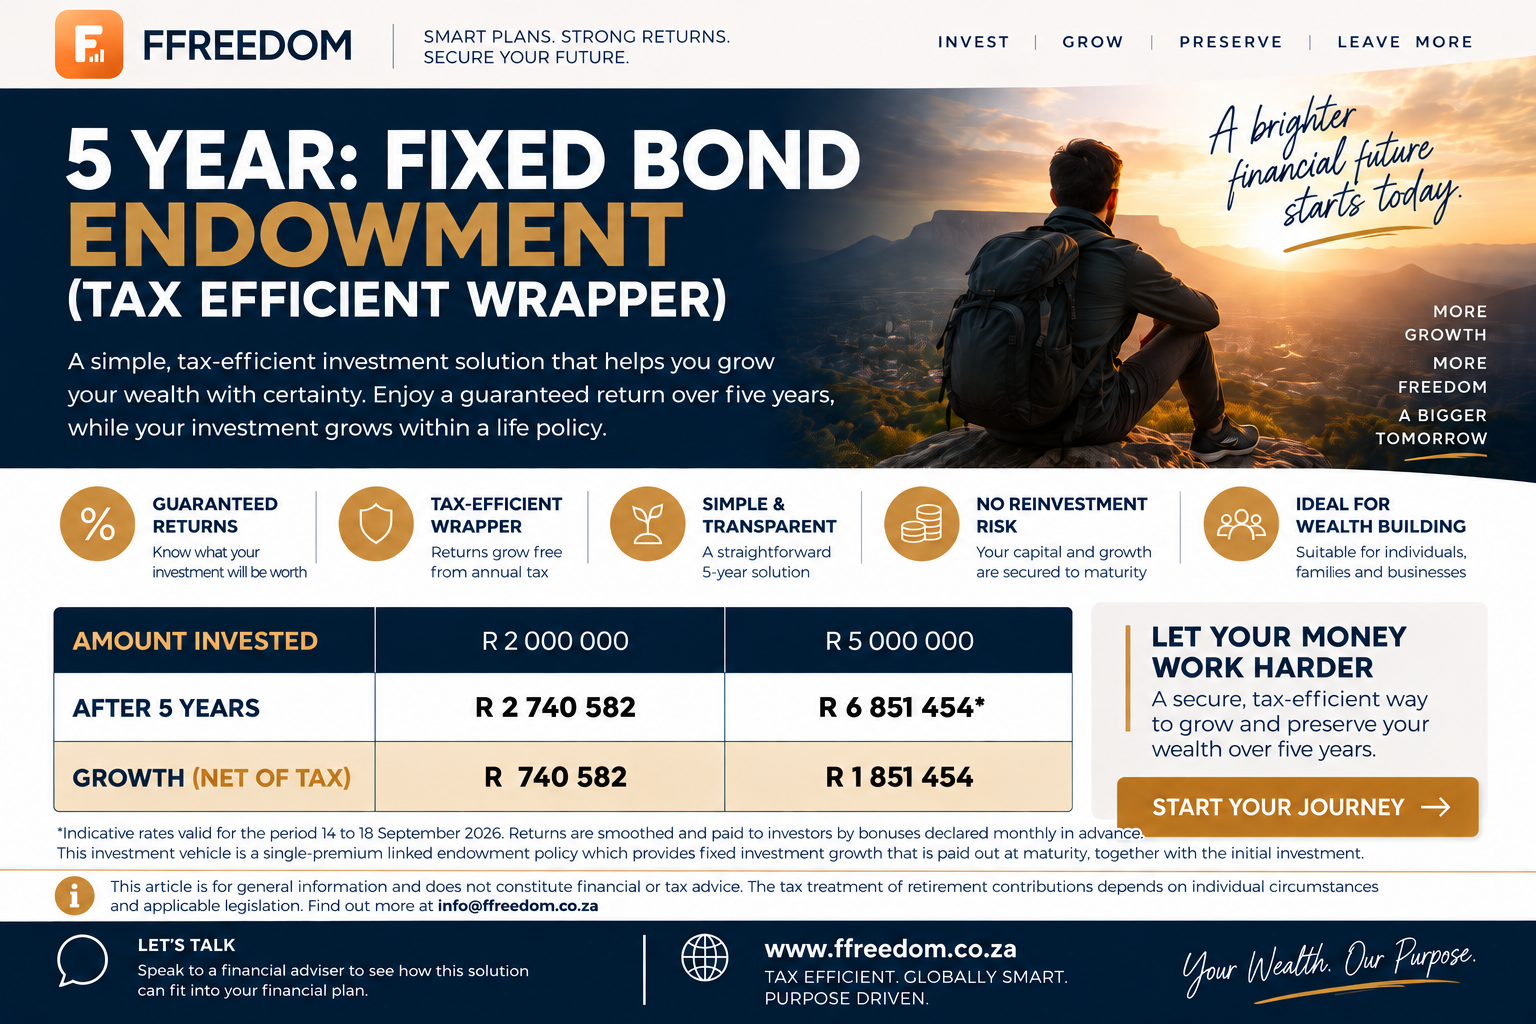
Fixed Bonds give South African investors a guaranteed, fixed growth rate over a five-year term, with both capital and maturity value backed by the Life Company. You lock in today’s rates, know your exact payout upfront, and avoid market risk, which makes this an effective low-risk parking vehicle.
Guaranteed maturity value
Your capital and growth are guaranteed by the Life Company, shown upfront in rands.
Tax-efficient outcomes
Rates are net of tax and the maturity value is not taxable in your hands.
Protection from rate cuts
Lock in today’s level and keep it, even if interest rates decline during the term.
Simple and predictable
One lump sum, a fixed five-year term, and a known payout date and amount.
Fixed Bonds provide a guaranteed, fixed growth rate over a five-year term, with both your capital and the maturity value backed by the Life Company. You lock in today’s rate at the start, know your exact payout upfront, and avoid market volatility. That certainty helps you plan without guesswork.
How a Fixed Bond works
When you invest in a Fixed Bond, your lump sum is placed for a single five-year term at a rate set on the day your policy starts. The growth is guaranteed and quoted net of tax within the policy, so the maturity value you see at the outset is the amount you will receive at the end of the term.
The guarantee is provided by the Life Company. Any guarantee is only as strong as the provider, and the Life Company’s capital strength underpins both your invested amount and the growth shown at the start. Your outcome does not depend on market movements or external asset managers.
A simple example in rands
As an illustration only: if you invested R100,000 at a fixed net rate of 7% a year for five years, your maturity value would be about R140,255. The actual rate you receive will be the one quoted when your Fixed Bond starts, and your guaranteed maturity amount will be shown in rands on your policy schedule.
The example is for information only, not advice. Ask for a personalised quote to see your exact guaranteed maturity value.
Who should consider this
Fixed Bonds are aimed at conservative investors who want a guaranteed return without exposing capital to market risk. They also work as a temporary parking vehicle for funds while you plan your next move, especially if you expect interest rates to decline and want to lock in today’s levels.
You want certainty about the rand amount you will receive on a fixed future date.
You prefer capital security over market-linked growth.
You value tax-efficient, net-of-tax quoted returns with no surprises at maturity.
You are comfortable committing funds for five years without needing regular access.
Fixed Bonds are not suitable if you require liquidity during the term or if you want exposure to higher, but uncertain, market growth.
Why guaranteed certainty matters
With a Fixed Bond, the outcome is pre-quantified. That means you can align the maturity date and payout with a specific goal, such as a home deposit, a child’s education, or a business expense. There is no need to forecast markets or track unit prices, because your return is set on day one.
This certainty also acts as an interest rate hedge. If rates fall more than expected, your return does not change. You continue to earn the guaranteed rate you locked in, protecting you from a lower-rate environment.
About the guarantee
Many products quote target maturities that depend on how underlying assets perform. Fixed Bonds are different: the capital and growth are guaranteed by the Life Company itself, not by third-party managers. As always, a guarantee is only as strong as the provider’s financial strength.
Tax and fees in plain language
Fixed Bond rates are quoted net of the policy’s tax, and the guaranteed maturity value is not taxable in your hands. You see your outcome upfront and, provided you stay to maturity, that figure is what you receive. This removes uncertainty about after-tax returns.
No income tax due on the maturity amount you receive as policyholder.
No capital gains tax in your hands at maturity for this policy-based structure.
The displayed rate is after policy-level tax, so there is no dilution later.
Advice fees can be built in or paid separately; if deducted from the bond, they will lower the maturity value shown on your quote.
Practical details you must know
The investment term is fixed at five years. You should invest money you can set aside for the full term, because early access is either unavailable or may require a surrender that reduces your payout. Think of this as a time-locked commitment in exchange for certainty.
You invest a single lump sum in rand. The Life Company confirms your guaranteed maturity value in writing before you proceed. Once issued, your rate and maturity amount are locked for the term.
Getting started is straightforward: request a personalised quote, review the guaranteed maturity value and any fees, and complete the application with your adviser or directly with the Life Company. Keep your policy schedule safe; it states the date and the rand amount payable at maturity.
How Fixed Bonds complement a plan
Fixed Bonds can sit alongside flexible savings and market-linked investments. They bring stability to a portfolio by ring-fencing part of your capital for a known future payout. This blend helps many investors meet near- to medium-term goals while leaving long-term growth to diversified market assets.
If you are unsure whether to prioritise certainty or growth for your goals, speak to a licensed adviser. An adviser can help you match timelines, risk tolerance, and liquidity needs to the right mix of solutions, including a Fixed Bond where appropriate.
Key take-out: Fixed Bonds give you clarity in rands from day one. If rates fall, your return holds. If markets swing, your outcome does not. For many South Africans, that is the calm corner of a financial plan.
Request a fixed bond quote
Request a fixed bond quote“I wanted certainty for a five-year goal. With a Fixed Bond I knew the exact rand amount I’d receive and could plan around that without worrying about market swings.”
Frequently asked questions
What exactly is guaranteed in a Fixed Bond?
Both your invested capital and the fixed growth to maturity are guaranteed by the Life Company. The guarantee relies on the provider’s financial strength and applies when you hold to the end of the term.
Can I access my money before five years?
Fixed Bonds are designed for the full five-year term. Early access is limited and may require surrender, which can reduce the payout. Only invest funds you can commit for the full period.
How are taxes handled on a Fixed Bond?
The quoted rate is net of tax within the policy. The maturity value is not taxable in your hands, so what you see on your policy schedule is what you receive if you hold to maturity.
How is this different from market-linked products?
Market-linked solutions can fluctuate with asset performance. With Fixed Bonds, your payout is pre-quantified and unaffected by market moves, because the Life Company provides the guarantee.
Who should consider a Fixed Bond?
Conservative investors who want certainty, capital protection and a known payout on a set date. It also suits those parking funds in anticipation of lower interest rates.
Request a fixed bond quote
You are leaving FFREEDOM and continuing to 1st Group Capital.
Request a fixed bond quoteThis is paid partner content. FFREEDOM's editorial team was not involved in producing it, and publication does not constitute an endorsement or financial advice. FFREEDOM is a product of 1st Group Capital (Pty) Ltd, an authorised financial services provider (FSP 49632).