The real question is not simply whether you have a Will. It’s whether your family is financially prepared to carry it out.
You’re seeing a lot more content about Wills in the media at the moment. That’s because the industry calls this “Will Season” — and the awareness is certainly needed.
But perhaps it’s worth looking a little deeper.
Having a Will is important, but being prepared for death is about more than having a signed document. If you died tomorrow, could your family access the money they need to carry out your wishes? What taxes, estate costs and transfer expenses could arise? And if a minor child inherits, how would those funds be managed?
Is Your Estate Ready?
Most people think a Will answers one question:
Who gets my assets when I die?
It does much more than that.
A valid Will in South Africa is the starting point for ensuring your wishes can be implemented, but it should also form part of a broader estate plan covering taxes, liquidity, property, family protection and the administration costs that arise when assets have to be transferred.
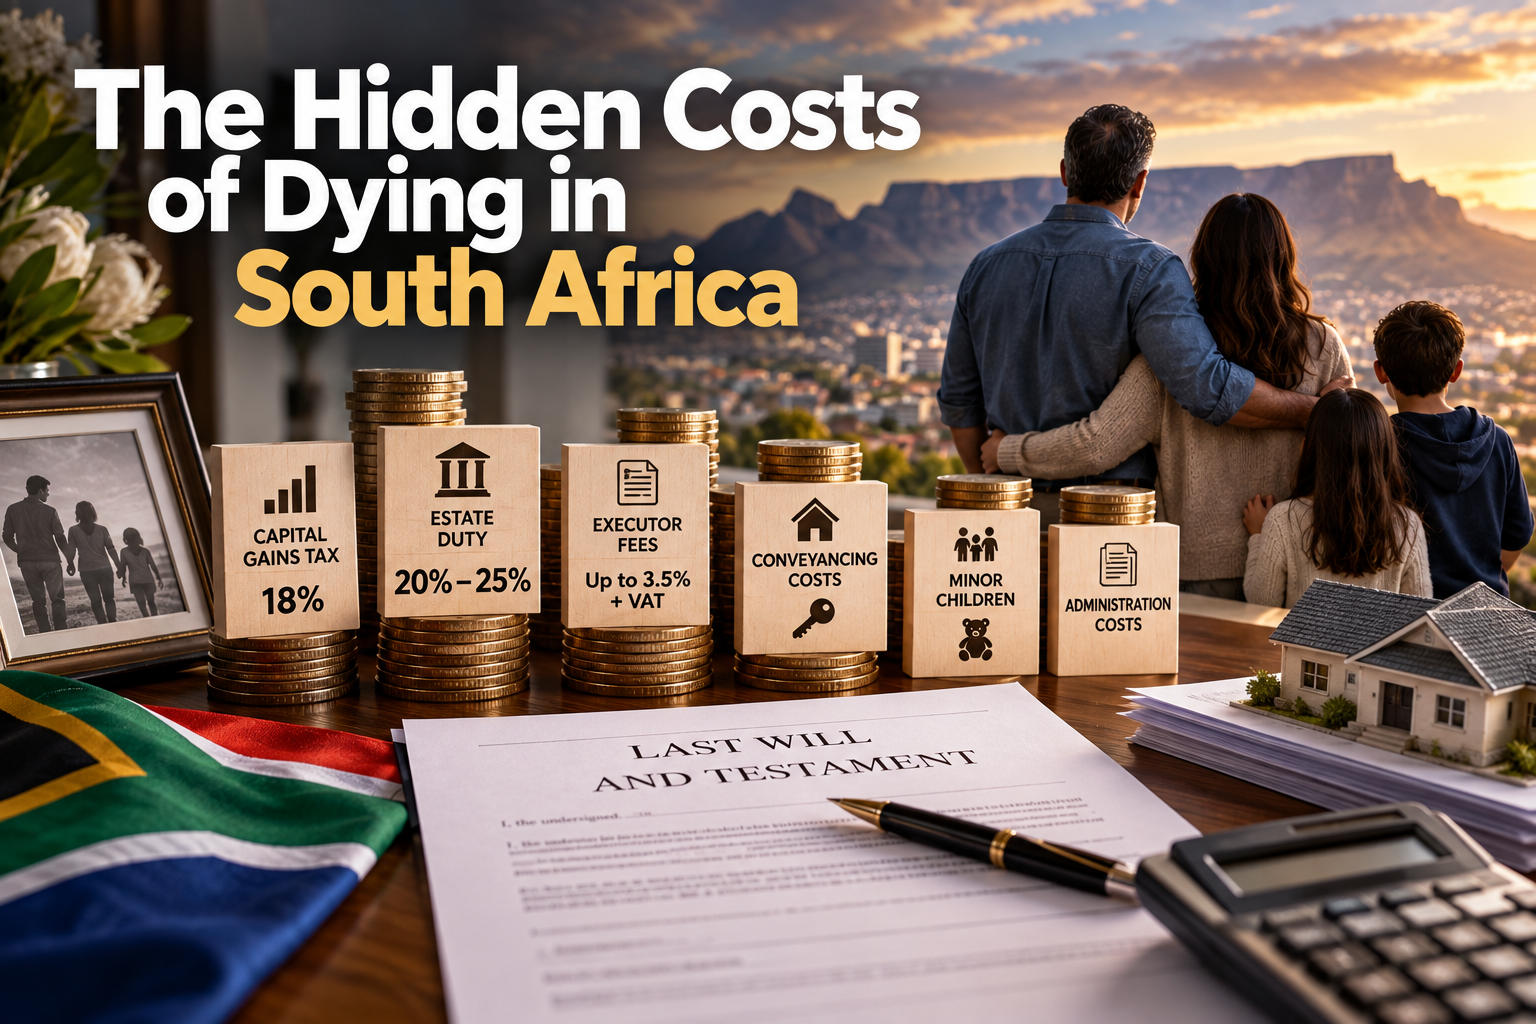
What many families underestimate is what happens financially at death. Our calculations show that you could lose up to 40% of your estate value.
Death can trigger a deemed disposal for Capital Gains Tax purposes, subject to the exclusions and rules in the tax legislation. For 2026/27, the maximum effective CGT rate for individuals and special trusts is 18%, while a specific death exclusion of R440,000 applies.
Then there is Estate Duty.
After allowable deductions and the R3.5 million abatement, Estate Duty is currently charged at 20% on the first R30 million of dutiable value and 25% above R30 million.
And taxes are only part of the equation.
An estate may also face executor fees, Master's fees, conveyancing and property-related costs, professional fees, debt settlement and testamentary trust administration.
The prescribed executor remuneration can be up to 3.5% of the gross value of assets, plus VAT where applicable.
Then comes an issue many parents never consider.
What happens if your beneficiary is a minor?
In South Africa, a minor is generally a person under 18.
If a minor inherits money and appropriate arrangements have not been made, funds may be paid into the Guardian's Fund, administered by the Master of the High Court.
While the Guardian's Fund exists to safeguard money belonging to minors and applications can be made for maintenance, education and other approved needs, accessing those funds involves a formal administrative process.
Your Will can provide for how a minor's inheritance should be dealt with, including appropriate trust arrangements.
This is why a Will should not be viewed as a once-off document.
It should be part of a financial plan that considers tax, liquidity, property, beneficiaries, children and the costs of transferring wealth.
What about the cost of winding up the estate?
There are insurance-based solutions designed specifically around estate costs.
Capital Legacy's Legacy Protection Plan, for example, provides indemnity benefits for qualifying executor, testamentary trust and conveyancing fees, together with liquidity and other benefits.
Capital Legacy is not the only provider operating in this space. Other estate-planning solutions include offerings from Sanlam, Momentum and Discovery, although the benefits, eligibility, underwriting, costs and structures differ between products.
This makes it important to understand exactly what an estate-cost solution covers rather than simply comparing monthly premiums.
The important questions include:
What estate costs are covered?
Is executor remuneration covered?
Are conveyancing costs included?
Are testamentary trust costs covered?
How much liquidity is available?
When does the benefit become payable?
What exclusions and conditions apply?
Is medical underwriting required?
Is the benefit sufficient for the size and complexity of the estate?
The important question is therefore not simply:
“Do I have a Will?”
It is:
“Will my Will and financial plan work together when my family needs them most?”
A valid Will is the start. Estate readiness is the plan.
👉 Download the FFREEDOM Estate Readiness Checklist and check whether your Will, beneficiaries, minor children, liquidity and estate costs have been properly considered.
This article provides general information and is not legal or tax advice. Individual estate planning should be reviewed with appropriately qualified legal, tax and financial professionals.
Sources
https://www.gov.za/faq/justice-and-crime-prevention/what-guardian%E2%80%99s-fund?
https://www.capitallegacy.co.za/legacy-protection-plan?
https://www.sanlamadvice.co.za/adviser/kholeka-sibiya/campaigns/sanlam-legacy?