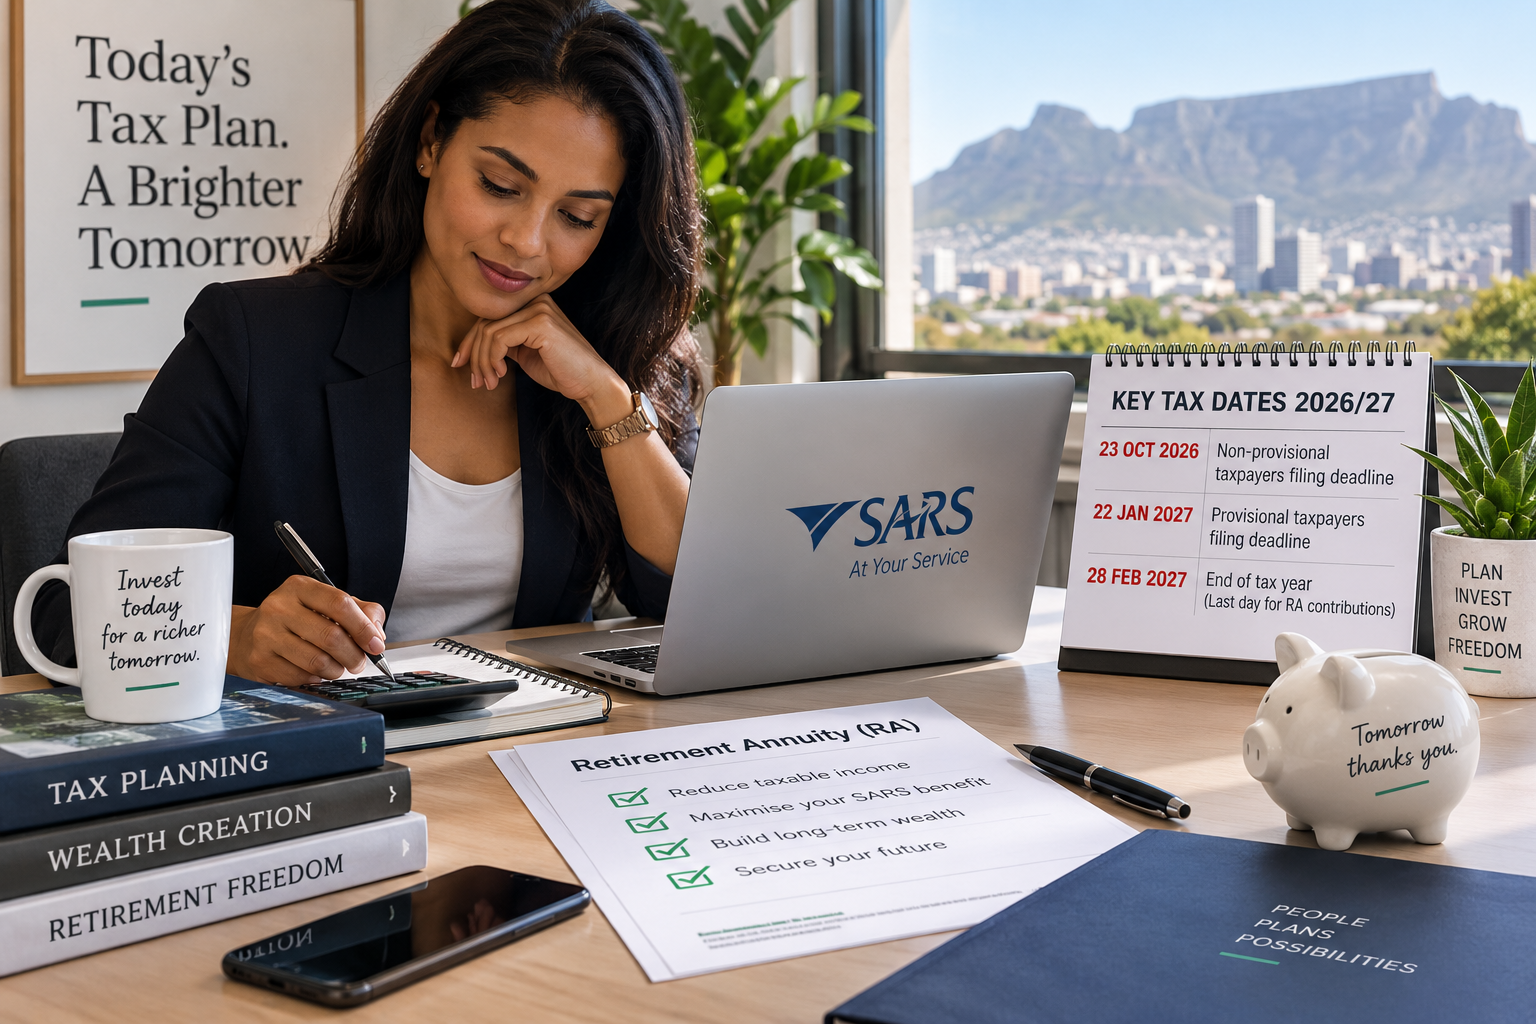
The filing deadline & the RA contribution deadline
Tax season is here — and for many South Africans, the 23 October 2026 filing deadline is approaching. SARS confirms that non-provisional individual taxpayers have until 23 October 2026 to submit their 2026 tax returns, while provisional taxpayers have until 22 January 2027.
But there is another date worth putting in your diary: 28 February 2027, the end of the 2026/27 tax year. This is the deadline that matters when planning qualifying retirement-fund contributions for that tax year.
For 2026/27, SARS confirms that contributions to pension, provident and retirement annuity funds are deductible at 27.5% of the greater of remuneration or taxable income, subject to an annual limit of R430,000. Unused qualifying contributions can be carried forward to future years.
The R430,000 Retirement Contribution Opportunity
For the 2026/27 tax year, qualifying contributions to pension, provident and retirement annuity funds can be deducted from taxable income, subject to the applicable limits.
The deduction is generally limited to 27.5% of the greater of remuneration or taxable income, subject to an annual maximum of R430,000. SARS confirms that this ceiling increased from R350,000 to R430,000 for 2026/27.
This does not mean that SARS simply pays 27.5% or 45% of your contribution back to you. Rather, the qualifying contribution can reduce the income on which you are taxed. Your actual tax saving therefore depends on your circumstances, including your taxable income and marginal tax rate.
For example, a qualifying R100,000 contribution could potentially reduce taxable income by R100,000, subject to the Section 11F limits. At a 41% marginal tax rate, the potential tax saving could be approximately R41,000, assuming the full deduction is available, and you have sufficient taxable income.
That means the effective economic cost of the contribution could be considerably lower than the amount invested.
Think Beyond the Tax Refund
The real opportunity is not simply the tax saving. It is what happens when the contribution remains invested for the long term.
An RA can provide a disciplined structure for retirement savings, with investment growth taking place within the retirement fund environment. The earlier contributions are made, the longer they potentially have to compound.
For higher-income taxpayers, the combination of tax deductibility and long-term investment growth can make retirement planning particularly relevant.
It is also possible to make larger contributions in some years and carry forward qualifying excess contributions for future deduction, subject to the legislation. SARS confirms that unused qualifying contributions can carry forward rather than simply being lost.
What About Front-Loading an RA?
Front-loading an RA is a financial planning idea designed for investors who may struggle to maintain a contribution commitment over many years. For some savers, making a contribution every month for decades can become difficult to sustain, particularly when the investment statement does not appear to change dramatically in the early years. This can lead to investment fatigue: the investor sees relatively modest growth and may be tempted to reduce or stop contributions before the real power of compounding has had time to take effect.
Front-loading changes the conversation. Instead of relying entirely on a small monthly contribution over a long period, an investor can consider making larger qualifying contributions earlier in their working life, where appropriate and within the applicable tax-deductibility rules. The objective is to get more capital invested sooner, giving it a longer period in which investment returns can themselves generate further returns.
Some products in the market also offer monthly bonus or loyalty allocations. Certain structures begin adding bonuses from around year five directly to the fund value, continuing periodically through to year 25, subject to the product's terms and conditions.
Importantly, under such a structure, an investor may contribute for the first five years and then stop making monthly contributions, while remaining eligible for the applicable bonuses through the specified period. This is the essence of the front-loading concept: put more capital to work earlier, allow the investment and applicable bonuses to compound over time, and potentially create a significantly larger retirement value.
For investors considering this strategy, the key is to understand the tax-deductibility limits, fees, guarantees, bonus conditions, investment performance and access restrictions. Used appropriately, front-loading can be a powerful way to put more capital to work earlier and potentially maximise the benefits of long-term compounding.
Don’t Wait Until February
Tax planning works best when it is done before the deadline.
Rather than waiting until February 2027 to find out how much you could contribute, speak to your adviser now about your income, existing retirement contributions, available deduction and long-term retirement objectives.
Your tax return looks backwards. Your RA contribution can help you plan forwards.
Speak to an adviser / complete the client contact form
This article is for general information and does not constitute financial or tax advice. The tax treatment of retirement contributions depends on individual circumstances and applicable legislation. Investment returns are not guaranteed and capital is at risk.